The take-off in African solar that official statistics can't yet see | Ember

The take-off in African solar that official statistics can’t yet see

Africa installs a record 17 GW of solar in 2026 – three-quarters of it is distributed solar, which is largely invisible

26 Aug 2026
14 Minutes Read
Download PDF
Dave Jones
Chief Analyst
Ember
Joel Nana
Research Director
African Tech Futures Lab

Highlights

17 GW
Solar installed across Africa in 2026 on Ember’s new estimates – up 45%, the third consecutive record year
100,000
Solar panels installed across Africa every day during 2026
75%
Africa’s solar growth in 2023-2025 that is likely from distributed solar – and is largely missing from official statistics

Executive summary

Africa’s solar take-off is confirmed

A year after Ember found the first evidence of a take-off in solar in Africa, a new methodology makes the boom measurable – and shows it running far ahead of the official record.

Key takeaways

01

Record solar capacity of 17 GW will be installed in Africa in 2026, up 45% year-on-year

Chinese exports of solar panels to Africa surged in the 12 months to June 2026, to levels similar to each of the Middle East and Latin America. This report introduces a new methodology, showing around 73% of Chinese imports globally have been installed, with an average six-month delay. This makes it possible to estimate full-year 2026 installations already. This shows 17 GW of solar was installed in 2026, equal to around 100,000 solar panels every day. That is a 45% rise year-on-year; 2025 rose by 51% and 2024 by 25%.

02

This is happening everywhere: 36 out of Africa’s 54 countries are expected to install record amounts of solar in 2026

19 countries have seen year-on-year growth of over 100%, including 544% in the Democratic Republic of the Congo (DRC), 282% in Zimbabwe, 176% in Egypt and 117% in Zambia. Solar growth used to be dominated by South Africa, but its share of African installations in 2026 will be below 20% for the first time since 2019, as other countries surge. Solar is now the single biggest addition to grid capacity in many African countries – Senegal will add solar capacity from 2023 to 2026 equivalent to almost 80% of its entire 2023 grid capacity, with DRC and Kenya adding more than half.

03

2026 new solar generation can meet Africa’s historic electricity demand growth

2026’s installations will generate around 23 TWh a year – 2.3% of Africa’s electricity generation, above the 2.2% average annual demand growth of 2014 to 2024. There are ten countries where 2026’s new solar will add more than 10% to annual grid electricity generation – Sierra Leone (97%), Togo (24%), Somalia (21%), Djibouti (21%), DRC (14%), Comoros (14%), Namibia (12%), Liberia (12%), Chad (11%), Lesotho (10%). Together these countries are home to 190 million people.

04

Half of the estimated rise in solar is missing from official statistics – because national reporting is so poor

Ember’s 2025 solar growth estimate is twice that of international statistics – 12.0 GW in 2025, compared with 6.2 GW from the International Energy Agency (IEA) and 4.6 GW from the International Renewable Energy Agency (IRENA). Ember forecasts annual installations in 2026 will rise another 45%, potentially increasing this gap further. However, international reporting can only be as good as national reporting, and that barely exists in many countries. We could only find official reporting for national solar capacity for 36 out of 54 countries; only 14 of those were for 2025, and even those 14 countries seem to underestimate the rise in solar. Only three countries – South Africa, Tunisia and Tanzania – publish some solar data monthly or quarterly.

05

Three-quarters of Africa’s solar growth is likely from distributed solar – and that is exactly what’s difficult to measure

Distributed solar, which is small-scale, customer-side solar installed mostly on rooftops – makes up most of Africa’s solar growth, and it’s the hardest type to measure. Ember estimates that 75% (20 GW of 26 GW) of the total solar capacity added between 2023 and 2025 is distributed solar. That’s because only a quarter of new solar can be explained by utility-scale and off-grid solar – utility-scale solar is fairly well-documented and visible through government procurement projects, and although off-grid solar is growing fast, its scale would still be very small in context of the gap.

This is the case even in countries with large utility-scale solar projects – in Egypt, for example, still 43% of its solar growth is estimated to be distributed.

There are just 12 countries that report an official or semi-official distributed solar figure, yet those still underestimate the growth. The lack of visibility on distributed solar is not unique to Africa, but a combination of factors makes it worse. A surge in companies, registries and licences show the solar rise is real.

06

Africa’s solar panel manufacturing will quadruple in 2026 – but for export, not for African rooftops.

Output will reach around 3.5 GW in 2026, a fifth of what Africa installs, led by new plants in Egypt and Tanzania aimed at the US market. 94% of panels installed in Africa are still imported from China, and huge Chinese cell and wafer shipments to Africa point to re-shipment rather than use in African solar panel manufacturing. Overall, manufacturing data quality is very poor, and it’s hard to state these numbers accurately.

The rise in solar capacity is likely to meet much of Africa’s electricity demand growth, and the sheer scale of cheap new supply could spur more demand growth too, creating huge human benefits.

Some of the solar is undoubtedly up-ending Africa’s diesel economics. Batteries, paired with solar, are the new diesel generator. A year of Chinese panel imports cost $2.4 billion USD; generating the same electricity from diesel would cost around that every three months. Africa is now importing more dollars of batteries than solar panels from China, led by Nigeria and DRC.

The rapid spread of distributed solar in sub-Saharan Africa is an underreported success story. However, since African countries are running blind to this change, they are not reflecting this rise in distributed solar in their plans. This will impact grid and battery investments. Countries also need to make sure they don’t overinvest in fossil fuel power plants that will sit idle.

It’s incredible seeing so many businesses and individuals, across so many African countries, choosing to install solar. Solar panels have become so cheap, the economics are compelling. But so much of this growth is hidden from view – national governments need to get better at gathering solar data. Countries are already leapfrogging into faster, more secure, cleaner energy growth, and the governments that get ahead of it stand to gain all the benefits.

Across Africa, distributed energy resources are rapidly expanding, and in many cases, overtaking grid capacity. This transition is chaotic and disruptive, and far from the orderly model planned in national strategies. Policymakers need to start responding to this shift. The choice now is whether these distributed assets remain a parallel power system that compensates for grid failure or are integrated in ways that unleash a wider range of benefits.

Chapter 1

Africa’s solar boom accelerates into 2026

Chinese solar panel exports into Africa surged in 2026. It is possible to use this to estimate solar installations for full-year 2026. This is happening in almost all African countries, and is enough to meet rising electricity demand.

1.1 Chinese solar panel exports surge

Chinese exports of solar panels to Africa surged to 23 GW in the 12 months to June 2026, a 53% rise on the 12 months to June 2025.

Almost all of this growth was driven by countries outside of South Africa; in 2023, 52% of Africa’s solar imports went to South Africa, and by June 2026 that share had fallen to 20%.

Chinese exports to Africa are now similar to both the Middle East and Latin America. In the 12 months to June 2026, China exported 23 GW to Africa, 23 GW to the Middle East and 25 GW to Latin America.

1.2 Historically, only around 73% of Chinese exports are installed

New global analysis shows how Chinese exports can be used to estimate installations in African countries.

Ember analysed the EU and five other countries over four years, comprising 368 GW of solar installations. All have fairly robust levels of data on annual installations and a fairly strong reliance on Chinese imports, so they can be used to help calibrate African installations from Chinese export data.

Chinese solar imports are a good proxy for installations, but there are two factors that can make them inaccurate predictors of actual deployment. First, panels are not installed at the time of shipping, so we apply a six-month time lag to Chinese exports, which is the approximate time-lag visible in the data, made up of 1-2 months’ shipping time from China, plus 4-5 months to move panels to site and install them. Second, we add three further adjustments to the Chinese data: solar panels imported from countries other than China (calculated from COMTRADE data), re-exports of solar panels, and domestically manufactured solar panels.

The results were that 73% of reported Chinese solar panels have been installed. There is a fairly high range from about 60-90% across years and across countries. 73% represents the total of the countries, weighted by installations, covering the full 368 GW of installations. In total, we consider that 73% is representative to apply to Africa. The box below explains why 73% is potentially even on the conservative side.

Why are “only 73%” of reported Chinese solar panel exports installed?

Ember has been analysing this global trend for years, and we believe it is a combination of four factors.

Chinese export values were likely slightly over-reported prior to April 2026. Chinese companies could claim VAT rebate (13% before December 2024 and 9% to end March 2026), which encourages them to over-report the value of their exports. This cannot be done indiscriminately, and historic literature suggests it could account for 5% over-reporting.

Exports are likely overestimated because solar panel prices fell so aggressively for so long. Chinese customs data reports only the value of solar panels – Ember converts this into megawatt capacity at spot prices. However, in a falling market, the price, which would have been agreed prior to shipping, is likely to have been higher than the spot price, resulting in overestimating the capacity.

Stocking of solar panels. Only 73% of solar panels are installed “so far”. That’s because many are in warehouses. In the EU, solar stocks reached around one year’s installation rate, so this can be significant.

Not all solar installed is reported. The 73% is calibrated against reported installations, not actual installations. Even in the EU and other advanced countries, there’s some evidence that reported data is missing some installations – especially for off-grid uses, which is often explicitly not included.

The 73% is likely to be conservative in the context of estimating solar installations in 2026. Factors 1 and 2 above are now effectively redundant in 2026: the VAT rebate ended from 1st April 2026, and the solar panel prices broadly stopped falling in late 2024. Of course, on factor 4, we are estimating actual not reported installations, so this isn’t relevant. Only factor 3, stocking, is relevant – especially in the context that solar sales are just picking up in Africa, so there is likely a lot of stocking of solar panels happening.

1.3 Africa solar installations rise 45% in 2026

It is possible to estimate solar installations for every country in Africa, using the methodology laid out in section 1.2 above. Furthermore, it’s possible to do this already for the full year 2026, because Chinese export data is already available until June 2026 and there’s a six-month delay to installations. The full calculations by country are available to download as an Excel file.

Ember estimates 17 GW of solar will be installed across Africa in full-year 2026. This is a 45% rise, following a 51% rise in 2025 and a 25% rise in 2024. That is an installation rate of 47 MW – around 100,000 solar panels – every day during 2026.

6% of solar panels installed were manufactured domestically, across a number of smaller plants in South Africa, Nigeria, Morocco, Algeria, Tunisia and Kenya. The remaining 94% were imported from China. In previous years, a small proportion were imported from outside of China – in India and South Korea – but these are now more profitable to sell into the US.

There is likely little re-export of solar panels from Africa so far. Although the US is reporting large imports of solar panels from some African countries, the data suggests this is likely Chinese solar cells and wafers rather than panels. There are re-exports of Chinese panels to other African countries, which we explore in chapter 1.4. There are also exports of domestically produced solar panels to the US, which we explore in chapter 3.

1.4 Solar is growing in all African countries

The solar boom is happening everywhere. 36 out of Africa’s 54 countries are expected to install record amounts of solar in 2026.

19 countries have seen year-on-year growth of over 100%, including 544% in the DRC, 282% in Zimbabwe, 176% in Egypt and 117% in Zambia.

Six countries are now gigawatt markets – we estimate South Africa will install 3.3 GW in 2026, 2.0 GW in Egypt, 1.7 GW in Nigeria, 1.7 GW in the DRC, 1.4 GW in Algeria, and 1.0 GW in Morocco.

One caveat – it may be that solar installations in some landlocked countries are underestimated, and the coastal countries overestimated. Ember’s analysis takes into account COMTRADE trade flows – e.g. Kenya into Uganda, and South Africa into Zimbabwe. However, that data is out of date, and in some cases isn’t reported at all.

Solar is now the single biggest addition to grid capacity in many African countries. Ten countries will each add at least 1 GW of solar between 2023 and 2026. Senegal will add the equivalent of almost 80% of its entire 2023 grid capacity, with DRC and Kenya adding more than half – while Egypt and Algeria, with two of the continent’s largest grids, will add less than a tenth. The most dramatic expansions are in the countries with the smallest grid capacity, where solar additions will match or exceed their entire existing national grid.

1.5 Solar could meet all of Africa’s electricity demand growth in 2026

Solar growth is enough to meet electricity demand growth in many countries and is helping to reduce diesel demand. And now that battery investment is stepping up, this growth could ultimately reduce the burden on the grid rather than increase it.

Half of African countries will see solar generation grow more than overall electricity demand

The scale of solar build in 2026 is roughly enough to meet Africa’s historic electricity demand growth.

The 17 GW of solar installed in 2026 would add 23 TWh of generation a year, assuming a conservative 15% capacity factor – equal to 2.3% of Africa’s annual electricity generation of 982 TWh in 2024. This is slightly more than the historic rise in electricity demand, which averaged 2.2% per year from 2014 to 2024.

In over half the countries in Africa – 28 out of 54 – the rise in solar generation will exceed the historic demand growth.

It is the countries with the smallest electricity systems that will see the biggest impact. There are ten countries where 2026’s new solar will add more than 10% to annual grid electricity generation – Sierra Leone (97%), Togo (24%), Somalia (21%), Djibouti (21%), DRC (14%), Comoros (14%), Namibia (12%), Liberia (12%), Chad (11%), Lesotho (10%). Together these countries are home to 190 million people.

Ironically, the two countries with the most new solar in 2026 – South Africa and Egypt – see their solar generation share increase below average, because they are also the two countries with by far the largest electricity systems. 2026’s new solar will add only 1.8% to South Africa’s electricity generation and 1.0% in Egypt’s, compared to the 2.3% African average.

Will solar actually increase electricity demand in Africa?

Electricity demand growth in Africa is low. It averaged 2.2% per year from 2014 to 2024, which is lower even than the global rate of 2.6%.

Solar has helped Pakistan to leapfrog to higher electricity demand growth, after years of paltry growth. In Pakistan, total electricity demand rose by 21% in just two years from 2023 to 2025, met entirely by the newly installed distributed solar generation.

But what’s more, Ember’s research showed this solar actually helped Pakistan’s electricity demand to rise – creating huge societal benefits.

Distributed solar was faster: in just two years, 27 GW of distributed solar was installed, equivalent to the capacity of all operating coal, gas and oil plants ever built in Pakistan. Distributed solar was cheaper – residential solar with a medium battery produces electricity at around PKR 20 per kWh, half the PKR 40 cost of grid electricity – air conditioning at grid prices is just unaffordable for many. Distributed solar was better – it eliminated daytime loadshedding, avoided more than $12 billion USD in oil and gas imports by February 2026, reduced CO2 and air pollution and saved transmission and distribution losses.

Like in Pakistan, many African countries have low electricity demand because of low electricity supply. Solar can help to drive the electricity demand growth that African countries need.

Solar is up-ending Africa’s diesel market, saving billions in diesel imports

The US-Iran conflict and the removal of subsidies in some countries, including Nigeria and Egypt, have led to a sharp rise in retail diesel prices. The economics before were compelling; now they are urgent.

Diesel generators are commonplace across the many countries in Africa which face unreliable electricity supply. A 2022 report from WoodMac showed at least 17 African countries have more distributed diesel generator capacity than they do grid-connected power-generation capacity.

Solar is undoubtedly being installed by people who own a diesel generator, to save money buying diesel. There is also a large amount of off-grid diesel that will be replaced with solar. Irrigation might be the biggest. In Pakistan, there is already an estimated 7 GW of solar tube wells providing irrigation – Morocco already had 40,000 solar irrigation pumps by 2020, and Egypt likely has a lot more. The use of solar to replace diesel generation at smaller, rich off-grid houses or tourist hotels is likely to have grown rapidly. Also, one company alone in Nigeria added 60 MW of solar to power phone masts.

This reduces imports – the import cost of a Chinese solar panel is a fraction of what the import cost of diesel would be for diesel generators. Generating the same electricity from a diesel generator as from a solar panel would cost as much in diesel, every three months, as the solar panel itself. Yet solar panels last for 30 years or more, saving significant costs on constant diesel top-ups.

The Chinese solar panel exports into Africa in the 12 months to June 2026 cost $2.4 billion USD, according to the Chinese customs agency; at $1.40 USD per litre of diesel, generating the same amount of electricity as those imported solar panels would need $2.4 billion USD of diesel every three months. So, in the hypothetical extreme scenario that all solar is displacing diesel generators, Chinese solar panels would save $2.4 billion USD on imports every three months, having paid for themselves in the first three months.

Africa already imports more dollars of batteries than solar panels

Since 2024, Africa has imported more dollars of batteries than solar panels from China. In the last two years, the value of solar panel exports doubled, but battery exports quadrupled.

The largest markets are Nigeria and DRC, where battery imports far exceed solar imports. In Nigeria, it’s likely that the batteries are purchased by households and businesses to provide electricity in loadshedding hours to replace buying diesel for generators. In the DRC many of the battery imports are linked to 24-hour solar+storage schemes at copper mines to replace diesel.

In most other markets, battery imports are less than solar. Egypt and Algeria have large utility-scale solar farms that aren’t yet installing a lot of batteries alongside, so all of that output is confined to daylight hours.

Batteries and solar will enable African countries to leapfrog to a new distributed grid, skipping the need to build a large national grid. The majority of electricity generation can be where it is used, day and night – either on rooftops directly, or embedded in megawatt scale (instead of gigawatt scale) in the local grid. Only a small grid is then needed to help balance supply and demand.

Chapter 2

Most of Africa’s solar capacity is distributed – and statistics aren’t capturing it

National reporting is inadequate – only three countries produce solar capacity data quarterly or more often, and even where 2025 reporting exists it misses a large amount of installations. These missing installations are thought to be mostly distributed solar.

2.1 The solar boom isn’t in official data yet

Ember’s 2025 solar growth estimate is twice that of international statistics

Ember estimates Africa installed 12.0 GW of solar in 2025; that’s around twice that of the International Energy Agency (IEA) of 6.2 GW and International Renewable Energy Agency (IRENA) of 4.6 GW.

Ember forecasts annual installations in 2026 will rise another 45%, potentially increasing this gap further.

IRENA published 2025 statistics initially in March, and then updated them in July. They show solar capacity stayed unchanged in 60% (32 out of 54) of African countries. The IEA published its renewables tracker last October. It has solar capacity data for 7 of the 54 countries, plus a total for Africa.

The biggest barrier to good international reporting is a lack of good national reporting. International reporting can only be as good as the national reporting beneath it – and the next section shows that it barely exists in many countries.

African countries need to improve their solar data reporting

Both the timeliness and quality of reporting are not fit for purpose in most countries.

In our analysis of national statistics, we could only find official reporting for national solar capacity for 36 out of 54 countries – and only 14 of those were for 2025. Even in those 14 countries reporting 2025 data, our estimates for what was installed in 2023-2025 alone far exceed the national cumulative capacity, suggesting that – where reported – solar capacity is not capturing all of the installations.

South Africa, Tunisia and Tanzania publish some solar data quarterly, and some even monthly. It’s increasingly common to do this internationally – Ember tracks 25 countries across the world that already report solar capacity monthly.

Why does accurate solar capacity reporting matter?

There are many implications of this underreporting solar growth.

First, in national and regional electricity planning. Distributed photovoltaic (PV) data is required to forecast net demand and future capacity needs. If it is excluded, planners may overestimate demand, procure unnecessary generation or select an unsuitable generation mix. The African Union’s Continental Power Systems Masterplan completely misses the solar trend: it shows 23 GW of solar forecast to be installed in Africa by 2040, which is less than the 26 GW estimated to have been installed in the last three years. South Africa’s IRP is perhaps the only national power plan in Africa that explicitly accounts for distributed generation.

Second, in system operation: System operators need the data for PV forecasting, dispatch, balancing and reserve planning. Without it, changes in midday demand and evening ramps become harder to predict and manage. Location-specific data supports assessments of hosting capacity, voltage, reverse power flows, congestion and protection requirements. Unregistered systems can therefore create technical and safety risks.

Third, in tariffs and utility planning: Reliable data is needed to assess changes in electricity sales, network use and utility revenues. Without it, tariffs and network charges may be based on incomplete assumptions.

Fourth, in policy monitoring: Registration allows governments and regulators to track market development, renewable energy (RE) targets and avoided emissions. Without consistent reporting, it is difficult to evaluate whether policies are working.

2.2 Most of the growth is in distributed solar – and no-one is measuring that

Three-quarters of Africa’s solar growth is likely from distributed solar

Africa installed an estimated 20 GW of distributed solar between 2023 and 2025.

Ember estimates Africa installed 26 GW of total solar between 2023 and 2025, yet only a quarter of new solar can be explained by utility-scale and off-grid solar, leading us to assume the rest is distributed solar. Global Energy Monitor (GEM) shows only 5.9 GW of utility-scale solar plants were built, and IRENA shows only 0.2 GW off-grid solar was installed. Utility-scale solar is fairly well-documented and visible through government procurement projects; therefore, there’s unlikely to be a big gap here. Off-grid solar is likely growing much faster than IRENA estimates, yet its scale would still be very small in the context of the gap.

In almost every country, over half of the solar is estimated to be distributed solar. Egypt added the second-most utility-scale solar, and yet 43% of its solar is still distributed.

Distributed solar is grid-connected solar on the customer side of the distribution network (i.e., “behind the meter”) and primarily for self-consumption. This is distinct from grid-scale solar farms interconnected into the high-voltage transmission network, and from any off-grid solar that isn’t connected to the electricity grid (like mini-grids or solar pumping irrigation systems). The vast majority of distributed solar installations are rooftop PV systems.

Explaining the rise in distributed solar

The rapid spread of distributed solar in sub-Saharan Africa is an underreported success story. Unlike in mature markets outside of Africa, where adoption has been concentrated in the residential sector and driven by generous government subsidies, adoption in African countries has been an organic response to falling technology costs, energy security, reliability needs, and, of course, compelling economics. Commercial and industrial customers have been the enthusiastic early adopters.

In most African countries, at least until recently, prosumers (households and businesses that both produce and consume their own power) would earn nothing for their exports, meaning systems get sized optimally for self-consumption. This explains why commercial and industrial customers — whose daytime load profile matches solar output — make up at least 80% of the total distributed solar installed capacity in most African markets with payback periods as short as 2-5 years.

The distributed solar boom has largely been on the back of China’s manufacturing glut, which drove module prices to record lows, together with the 2022 oil crisis linked to the Russia-Ukraine war. Where policy played a role, it rarely targeted distributed solar directly. South Africa lifted its generation licensing threshold in the middle of the worst loadshedding on record, and some 7 GW of distributed capacity followed, much of it through private wheeling, where businesses buy power directly from off-site generators.

Zambia opened its market to private supply in 2023 after drought cut its hydropower generation by nearly 90% – its worst in decades. Nigeria removed its fuel subsidy in May 2023 and sharply raised tariffs for its high-paying ‘Band A’ customers the following year, making self-generation the cheaper option for anyone with access to capital. Kenya, on the other hand, and the vast majority of African markets, needed no trigger at all, as expensive electricity and unreliable supply were sufficient to stir investments in these distributed assets.

African countries need expanded frameworks that anchor these unplanned, grid-edge distributed assets in a coherent national strategy, particularly in light of shrinking aid flows, mounting energy security pressures, fragile utilities, and the unfinished business of universal electrification. This all starts with gaining visibility.

Why so little distributed solar is visible – and why that’s changing

The lack of visibility on distributed solar is not unique to Africa, but a combination of factors makes it worse here. Many installations are carried out informally. This is compounded by the absence of distributed generation regulation, which leaves privately owned assets with no formal route into the market, and therefore no incentive to register themselves. And even where such regulations exist, they are often not operationalised.

Countries with even minimally operational regulation, licensing and permitting do have some visibility, although rarely much. About 12 report an official or semi-official distributed solar figure — net-metering registers, captive-power licences, or utility estimates, according to research from Sustainable Energy Africa. In some of them, Ember’s estimate of the capacity added in just the last three years exceeds the entire official stock recorded across all years. Tunisia and South Africa, which have among the oldest and most robust policies, regulations and permitting procedures on the continent, are also the two countries showing the smallest share of unrecorded distributed capacity.

That tide is now shifting, as governments take notice and system operators are stepping up to streamline registration and permitting for this increasingly important market segment. At least 15 African countries have registration and permitting procedures at an advanced draft stage, with several more in force or running as pilots. These are mostly reactive, and still behind the pace of the market, but are nonetheless expected to start closing the statistical gap. South Africa has gone a step further, building a digital platform for small-scale embedded generation, now used by more than 55 municipal distribution utilities, which moves permitting online and captures each installation’s geolocation. Eswatini and Namibia will launch theirs in early September 2026.

2.3 Further evidence on the ground

A surge in companies, registries and licences shows the solar rise is real

In Nigeria, 370 new solar companies registered in 2025, almost seven times higher than the 56 registered in 2019. In South Africa, GreenCard installer certifications show 638 installation companies certified in 2023 alone as solar installations boomed from chronic loadshedding. In Kenya, EPRA’s register of licensed solar firms in 2023/2024 was around six times that of 2019/2020.

2.4 What next for policy?

Distributed solar is driving the biggest disruption of Africa’s power system from the bottom up, funded by private investment. Fundamentally about access, affordability and reliability, these assets also help defer new infrastructure upgrades and free up capacity on already overloaded transformers and substations in urban nodes. On the other hand, forcing businesses into self-generation at two to four times the all-in cost of utility-scale capacity is a hard foundation for industrial competitiveness. And every large customer that reduces its dependence on the grid takes with it the revenue that cross-subsidises poorer households, worsening the position of an already precarious supply industry.

If anything, Africa needs better planning — planning that constructively embeds these distributed assets so that they support the grid, and so that the benefits are shared across a wider base.

Chapter 3

Africa’s solar panel manufacturing rises – but for export, not domestic demand

New large solar panel manufacturing plants have come online in Egypt and Tanzania, and other gigawatt-scale plants are planned. This should bring value-add for many countries, even though it has a strong reliance on Chinese inputs. The immense reported exports of Chinese cells and wafers to Africa far exceed the scale of Africa’s solar panel manufacturing needs, and suggest large-scale reshipping.

3.1 Africa’s solar panel manufacturing will likely quadruple in 2026

Africa’s solar panel manufacturing will quadruple this year as new large plants come online in Egypt and Tanzania to around 3,500 MW (Egypt 2,000 MW, Tanzania around 500 MW, six others around 1,000 MW), compared to around 800 MW in 2025.

This is equal to 20% of the 17 GW of solar panels installed during 2026. However, in both markets, the solar panels are predominantly for export to the US, where prices are much higher than for Chinese panels due to US tariffs on Chinese goods. The panels installed in Africa are predominantly Chinese-imported panels.

Ember estimates 2026 manufacturing output will be 2,000 MW in Egypt and around 500 MW in Tanzania – both up from near-zero in 2025. In addition, smaller plants in other countries are estimated to add a further 1,000 MW in 2026, more than doubling from 460 MW in 2024.

However, the data to assess this is extremely limited. There seems to be little documentation of the status of solar plants – either by governments or publicly elsewhere.

A large Ethiopian solar plant came online in 2025, manufacturing wafers into cells for sale to the US, where they are turned into solar panels. We exclude it here, since we are looking at only solar panel manufacturing.

Egypt and Tanzania built for US export

Ember’s 2026 production estimate of 2,000 MW is based on EliTe’s output ramping quickly up to full capacity, and no output yet from the Sunrev plant. Customs data shows this 2026 ramp may be slower: Egyptian customs data shows US solar panel exports ramped up to 48 MW by April 2026, and the US reports zero imports as yet from Egypt. However, Chinese cell and wafer reported exports were much larger, at 2.4 GW of cells and wafers in the first half of 2026 alone, suggesting a large step-up in production is coming.

In Egypt, the rise in solar manufacturing is only just beginning. There are three large solar panel manufacturing plants – one began production at the start of this year, another started shortly after, and another is due to begin in early 2027.

  • EliTe Solar began production at Ain Sokhna around the turn of the year, inaugurated by Egypt’s prime minister on 11 January 2026. Its $115mn USD complex pairs 2 GW of cells with 3 GW of modules and employs about 800 people, roughly 700 of them Egyptian.
  • Sunrev Solar laid its cornerstone in June 2025 targeting production in the first half of 2026, though no start was confirmed by July, so we assume no output from it this year. Its $200mn USD plan adds 2 GW each of cells and modules; a second phase making wafers would be Africa’s first.
  • ATUM Solar – JA Solar with Global South Utilities, Infinity Capital and Egypt’s AH – broke ground in December 2025 for early 2027. Its $210mn USD project adds 2 GW each of cells and modules, and carries the only commitment by an African plant to buy local glass and aluminium.

In Tanzania, there is just one plant: Tanzol’s building at Kwala, in Kibaha, with a reported $300 million USD first phase and operations said to have been relocated from Vietnam and China. A special economic zone official confirmed in May 2026 that it is running, but no start date or capacity has been published. Reports imply it could be as big as 2 GW per year, but there is no confirmation of this.

Ember’s 500 MW Tanzanian estimate is very much a guess. US customs isn’t reporting any imports yet in its data to April 2026 (and Tanzania customs doesn’t report data either way). However, Chinese customs data does report large exports of cells – 945 MW in the first half of 2026 – and also 1,481 MW of wafers (although no known Tanzanian plant could use wafers). Some is feedstock; some may simply be passing through.

Other African countries supporting domestic growth

Meanwhile, six further countries have a smaller amount of solar panel manufacturing, which has been rising as more plants come online or have been expanded. We estimate 2026 output in Nigeria and South Africa will triple compared to 2024, Morocco and Algeria will double, and also Tunisia and Kenya will rise.

Nigeria’s output has risen because a second large line – LPV Technologies’ 200 MW plant in Lagos – started up in January 2025, joining incumbents Auxano, NASENI and Blue Camel. Its rural electrification agency puts national capacity at 300 MW, up from 120 MW two years earlier, though no Nigerian manufacturer publishes output.

Nigeria’s pipeline is large but stalled. Tranos broke ground on an 800 MW plant in June 2025 but has not commissioned its first line; the 1 GW Solarge–InfraCorp hub has neither construction nor a site; Oando’s 1.2 GW is a pre-investment decision.

In Morocco, two 1.2 GW plants have been proposed, but both are at early stages of development.

New US tariffs may hurt exports – but may ultimately support domestic installations

Trump announced new tariffs on solar cells and panels, which will make all imports of cells and panels much more expensive from 1 December 2026. It will reduce the ability for Egypt, Tanzania and Ethiopia to sell panels and cells into the US.

The premium is also closing from the other side: China removed its 9% export VAT rebate on 1 April 2026, lifting Chinese panel prices 4-8% and improving the economics of an African-made panel sold in Africa.

This could mean solar panels end up being used domestically. This would replace Chinese imports and ultimately mean Africa becomes more directly self-sufficient.

3.2 Africa’s solar manufacturing has a large Chinese reliance, though there is some local value-add

Both the Egyptian and Tanzanian plants are value-adding to the national economies, despite a strong Chinese reliance. But of the two large plants that have come online in 2026, the value-add is very different.

The Egyptian plant includes cell manufacturing and is using new production lines. The Tanzanian plant is for panel assembly only and seems to use older, relocated production lines, running on Chinese cells.

Egypt is manufacturing cells, and has plans for wafer, glass and frames manufacturing, but overall progress is slow to go beyond importing components. No solar glass is made anywhere in Africa (including even in South Africa); a proposed $700mn USD Suez plant would be first. All EVA, backsheet, ribbon and junction boxes are thought to be imported.

India provides a good example of building industrial strategy for solar and batteries, and is one of the few countries to properly scale supply chains that can compete on price with China.

3.3 Imports of cells and wafers are not a good proxy for African panel manufacturing

China exported ten times as many cells and wafers to Africa as Africa has manufactured solar panels, according to import data from Ember’s China’s Solar PV Export Explorer. 28 GW of solar imports – 19 GW of cells and 9 GW of wafers – compared to just 2.7 GW estimated to have been manufactured in the 2.5 years to June 2026. In fact, 19% of Chinese solar cell exports and 13% of wafer exports in H1-2026 were destined for African countries.

We think that, in a small part, this reflects the step-up in African solar manufacturing that will continue into late 2026 and beyond.

But we think the majority would not actually be imported into the country, but rather re-shipped most likely to the US. Customs in most African countries do not report imports of cells and wafers, so there is no data there that helps to clarify.

Ethiopia imports cells, yet there is no manufacturing capacity to convert and build them into panels. Tanzania and Kenya reportedly received large exports of solar wafers from China, despite having no manufacturing plants to convert them into cells. Nigeria imported 3.1 GW of solar cells in the 12 months to June 2026, which far exceeds its small manufacturing capability.

Therefore, these Chinese exports give few insights into African solar panel manufacturing.

Supporting materials

Acknowledgements

Contributors

Ember: Matt Ewen, Daan Walter, Kingsmill Bond, Nic Fulgham, Kostantsa Rangelova, Rini Sucahyo, Rashmi Mishra, Sachin Sreejith and Chelsea Bruce-Lockhart.

Reviewers

We thank our external reviewers Mark Clinton Thurber (Stanford University), Rose Mutiso (African Tech Futures Lab), Tanaka Shumba-Mukudu (Sustainable Energy Africa) as well as Bhoomika Tiwari and Chris Gross (GET.transform).

Cover image

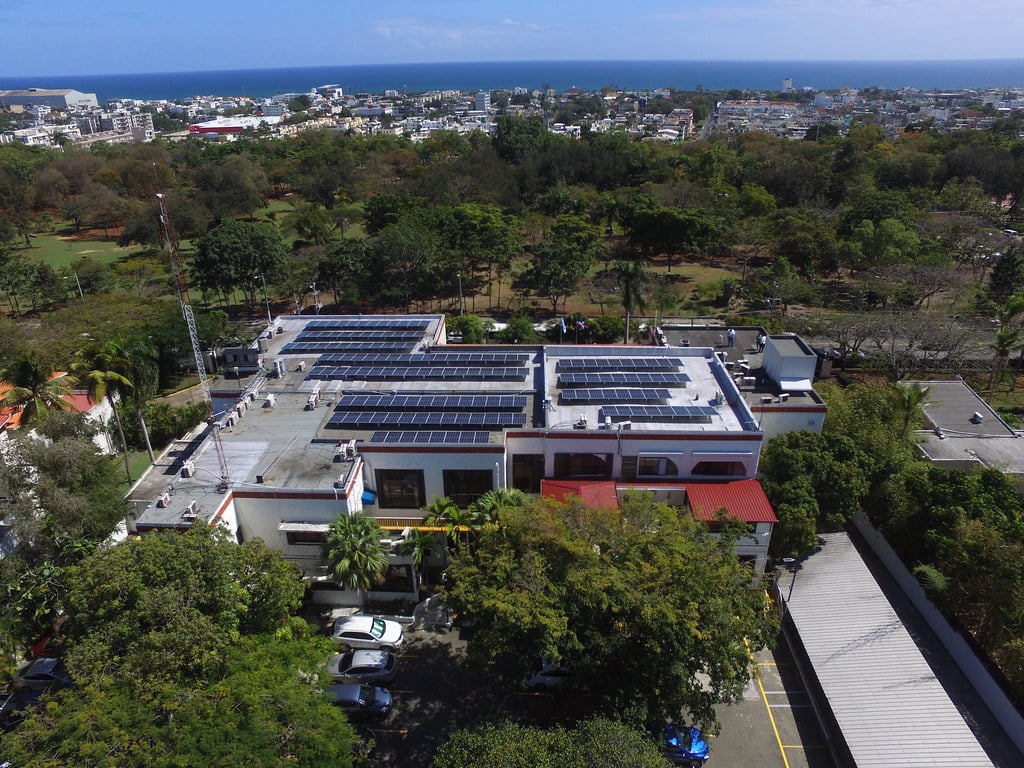
Aerial view of rooftop solar in Africa

Credit: Sustainable Energy Africa

Share